
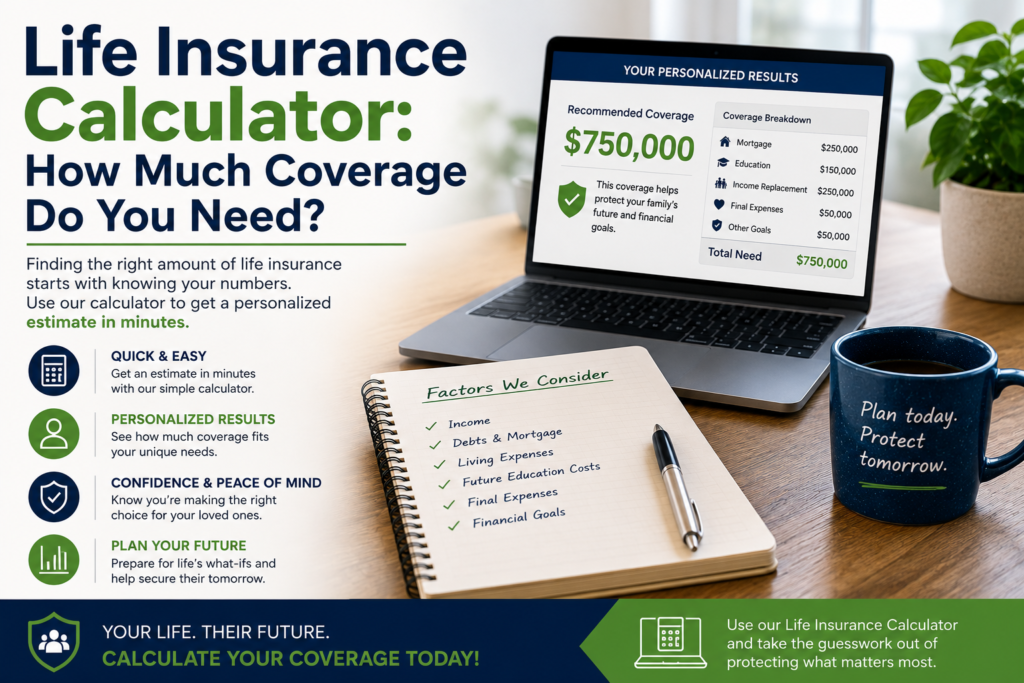
The most common life insurance mistake isn’t picking the wrong company — it’s picking the wrong coverage amount. Buy too little, and your family faces the exact financial gap insurance was supposed to prevent. Buy too much, and you’re overpaying for years or decades. Rules of thumb like «10 times your income» are a reasonable starting point, but they don’t account for your actual debts, how many years of support your family needs, or whether you already have savings and existing coverage. Use the calculator below to get a more personalized estimate, then read on to understand exactly how the number is built.
Quick Answer: The Rule-of-Thumb Method
If you want a fast, rough estimate before diving into the details, the most commonly cited rule of thumb is 10 to 15 times your annual income. So someone earning $75,000 a year might target somewhere between $750,000 and $1,125,000 in coverage. This method is easy to apply but doesn’t account for your specific debts, number of children, or existing assets — which is exactly why the calculator above uses a more complete method.
The Three Main Methods for Calculating Coverage
Income multiplier method (simplest). Multiply your annual income by a factor, typically 10-15x. Easy to use, but it ignores your actual debt load, number of dependents, and existing savings.
DIME method (most commonly recommended). DIME stands for Debt, Income, Mortgage, and Education. You add up your non-mortgage debt, the years of income you want to replace, your remaining mortgage balance, and estimated future education costs for your children, then subtract existing savings and coverage. This is the method our calculator above uses, because it reflects your actual financial picture rather than a flat multiple of income.
Human life value method (most detailed, least common for DIY use). This method estimates the full economic value you’ll contribute over your remaining working years — future income, benefits, and services — minus your own future consumption, discounted to present value. It’s more precise but complex enough that it’s typically used by financial professionals rather than as a quick self-service calculation.
For most families, the DIME method strikes the right balance between accuracy and simplicity, which is why it’s the basis for the calculator on this page.
Breaking Down the DIME Method
Debt — Add up non-mortgage debt: credit cards, auto loans, personal loans, and student loans. The goal is making sure these don’t become a burden your family has to manage without your income.
Income — Decide how many years of income you want to replace. A common approach is covering the years until your youngest child is financially independent, though some families choose a flat number like 10-20 years regardless of children’s ages.
Mortgage — Your outstanding mortgage balance. Many families prioritize this specifically because keeping the family home is one of the most important forms of stability after losing a primary earner.
Education — Estimated future education costs for your children, if that’s a priority for your family. This is optional and depends entirely on your own goals — not every family chooses to fund this through life insurance.
Once you’ve added these four categories together, subtract your existing liquid savings and any current life insurance coverage you already have in force. The result is a reasonable estimate of the additional coverage you need.
Worked Example
Consider a 35-year-old parent earning $80,000 a year, with two young children, a $280,000 remaining mortgage balance, $15,000 in non-mortgage debt, and $40,000 in existing savings and a small employer-provided policy:
- Debt: $15,000
- Income replacement: $80,000 × 15 years = $1,200,000
- Mortgage: $280,000
- Education (optional, two kids): $150,000 ($75,000 each, a common planning estimate)
- Subtotal: $1,645,000
- Minus existing savings/coverage: −$40,000
- Estimated coverage need: $1,605,000
This comes out well above the simple «10x income» rule of thumb ($800,000) because it accounts for the mortgage and education goals specifically — which is exactly the kind of gap a flat multiplier misses.
Adjusting the Calculation for Your Situation
If you’re a stay-at-home parent, the income replacement figure doesn’t apply the same way since there’s no salary — instead, estimate the cost of replacing childcare, transportation, and household management, commonly $250,000-$500,000. (See our guide to life insurance for stay-at-home parents for a full breakdown.)
If you’re self-employed or a business owner, consider whether your coverage needs to account for business debts, a buy-sell agreement with a partner, or key-person coverage — these go beyond personal DIME calculations and are worth discussing with a financial professional.
If you’re within 10-15 years of retirement, you may need less income-replacement coverage and more focus on final expenses, remaining debt, and any legacy goals, since fewer working years remain to replace.
If you have a child with lifelong care needs, a flat number of income-replacement years may understate what’s actually needed — permanent life insurance or a properly funded special needs trust may be more appropriate than a standard term calculation.
Term Length: Matching Coverage to Time, Not Just Amount
The DIME method tells you how much coverage to buy — but you also need to decide how long that coverage should last. A common approach: match your term length to the number of years until your youngest child is financially independent, or until your mortgage is paid off, whichever is longer. A new parent with a 30-year mortgage often ends up around a 25-30 year term, while a parent with older teenagers might only need 10-15 years.
Frequently Asked Questions
Is 10 times my salary enough life insurance? It can be a reasonable starting point, but it doesn’t account for your mortgage balance, other debts, number of children, or existing savings. The DIME method (debt + income replacement + mortgage + education, minus existing assets) generally produces a more accurate, personalized number.
Should I include my mortgage in my life insurance coverage amount? Many financial professionals recommend it, since keeping the family home is often a top priority after losing a primary earner. If you’d rather your family downsize or use other assets to cover the mortgage, you can reduce or exclude this portion of the calculation.
Do I need to fund my children’s education through life insurance? It’s optional. Some families specifically want to guarantee college funding even in a worst-case scenario, while others treat education as a lower priority than the mortgage and basic income replacement. Include it only if it reflects your actual goals.
How often should I recalculate my coverage needs? Revisit the calculation after major life events — a new child, a new mortgage, a significant raise, paying off debt, or a spouse changing employment status. Many families also do a general check-in every 3-5 years even without a specific trigger.
Does this calculator account for inflation? Not directly — the estimate reflects today’s dollars. If you’re buying a long-duration term policy (25-30 years), keep in mind that a fixed death benefit will have somewhat less purchasing power decades from now, which is one reason some buyers add a cost-of-living rider.
Bottom Line
A quick income-multiplier estimate is better than no estimate at all, but the DIME method — debt, income replacement, mortgage, and education, minus existing savings — gives a far more personalized picture of what your family would actually need. Use the calculator above to get your number, then compare quotes from a few insurers once you know roughly how much coverage to shop for. If your situation includes something the standard method doesn’t capture well — self-employment, a special needs dependent, or a complex estate — it’s worth a conversation with a licensed financial professional in addition to running the numbers yourself.
This tool and article are for general informational purposes only and do not constitute financial, legal, or insurance advice. Your actual coverage needs depend on your complete financial picture — consult a licensed financial advisor or insurance agent for personalized guidance.